Most policies overlook motorized awning damage, yet proper documentation and wind rating can secure coverage and avoid costly claims.
Ever wondered why your homeowner's policy seems silent when a storm snaps your motorized awning? The answer often lies in the fine print and the way insurers view outdoor equipment.
Understanding the insurance landscape helps you avoid surprise denials, especially in Austin where intense sun and sudden gusts are common. This guide walks you through the key steps to keep your awning protected.
Key Takeaways
Document wind ratings, keep installation photos, and verify UL certification to strengthen your claim and reduce premium impact for motorized awnings.
- Document Wind Rating: Capture the exact wind class from your installer; insurers often require a rating of at least 20 mph for coverage.
- Photo Evidence: Take clear images of brackets, fabric, and motor before and after storms; visual proof speeds claim processing.
- UL Certification: Verify that the motor and hardware carry UL marks; this can lower liability costs and improve premium rates.
- Permit Records: Keep building‑permit copies; they demonstrate compliance with local codes and support your claim’s legitimacy.
- Professional Installer: Choose a local expert who knows Austin’s wind patterns and can provide detailed installation reports.
Why Most Homeowners Insurance Policies Don't Cover Motorized Awning Damage
Insurance carriers often treat awnings as optional accessories rather than essential building components. This classification means many standard policies exclude damage unless a rider is added. In Austin, where summer heat drives frequent awning use, that exclusion can leave homeowners exposed.
The exclusion stems from a combination of perceived low risk and the difficulty of verifying proper installation. When a storm hits, insurers may question whether the awning met local wind‑rating standards, leading to claim denial.
Key Exclusions
- Standard Exclusion: Most policies list awnings under “other structures” and require a separate endorsement for coverage.
- Undocumented Wind Rating: Without a certified rating, insurers assume the awning cannot withstand typical gusts, triggering denial.
- Improper Installation: If brackets are not anchored to structural framing, insurers cite negligence and reject claims.
- Electrical Component Limits: Motor wiring must meet NEC standards; otherwise the electrical portion is deemed uninsurable.
- Age of System: Older units lacking modern safety sensors are often excluded as high‑risk items.
Because insurers default to exclusion, the safest route is to proactively add a rider and keep detailed records. In practice, homeowners who secure a wind‑rating endorsement see far fewer claim rejections, especially after Austin’s spring thunderstorms.
The Wind Rating Your Installer Should Document for Your Insurance Claim
Wind rating is the single most critical data point when filing a claim for a motorized awning. The rating, expressed in miles per hour, tells the insurer how much force the system can safely endure before retraction is required.
In Austin, wind speeds during a thunderstorm can easily exceed 20 mph, so a rating of at least 25 mph for the extended position is advisable. Documenting this rating protects you from disputes about whether the awning was adequately designed for local conditions.
A quick comparison of common wind‑rating tiers helps you choose the right level for Austin’s climate.
| Rating Tier | Maximum Extended Speed | Typical Use Cases |
|---|---|---|
| Class 1 | 15 mph | Light residential awnings in low‑wind zones |
| Class 2 | 25 mph | Standard residential awnings across most of Austin |
| Class 3 | 35 mph | High‑performance systems for exposed patios |
Rating Essentials
- Manufacturer Rating: Obtain the exact wind‑class number from the product sheet; it is usually listed by the brand such as Somfy.
- Installation Certification: Ask the installer to sign a report confirming the awning meets ASCE 7‑16 wind load calculations for your address.
- Sensor Calibration: Ensure the wind sensor is set to retract at the manufacturer‑recommended speed, typically between 15‑25 mph.
- Local Code Alignment: Verify that the rating satisfies Austin’s building‑code wind requirements, which reference the International Building Code.
- Record Keeping: Store the rating sheet in a digital folder alongside the warranty and permit documents.
When your installer provides a clear, code‑compliant rating, the insurer can verify that the awning was built for the local wind environment, making claim approval far more likely.
What Happens When Your Awning Fails During a Storm Without Proper Coverage
A sudden gust can rip a fabric panel or bend an arm, leaving the awning unusable. Without proper insurance, the cost of repair or replacement falls entirely on the homeowner, often exceeding $2,000 for high‑quality motorized systems.
Beyond the immediate expense, a damaged awning can expose windows to direct sunlight, increasing cooling loads and utility bills. In Austin’s hot climate, that extra heat can add noticeable discomfort and higher energy costs.
Consequences
- Out‑of‑Pocket Repair: Homeowners must fund labor and parts, which can total several thousand dollars for motor and frame replacement.
- Energy Penalty: Loss of shade raises indoor temperatures, forcing air‑conditioners to work harder and raising electricity usage.
- Safety Risk: A partially retracted awning may become a pinch‑point hazard, especially for children playing nearby.
- Property Damage: Water can seep through torn fabric, damaging siding or interior walls if the awning no longer deflects rain.
- Insurance Premium Spike: Future policies may be priced higher after a claim denial, reflecting perceived risk.
The financial and safety impacts of an uninsured failure quickly outweigh the modest cost of adding a rider. In practice, homeowners who secure proper coverage avoid surprise expenses after Austin’s frequent summer storms.
How UL Certification Affects Your Liability Protection and Premium Costs
UL certification signals that a motor and its components have passed rigorous safety testing. Insurers view UL‑listed hardware as lower risk, which can translate into reduced liability premiums for the homeowner.
In Texas, the U.S. Consumer Product Safety Commission encourages the use of UL‑certified outdoor equipment. When a motorized awning carries the UL mark, the insurer can confidently assess that the electrical system meets national safety standards.
Key differences between UL‑certified and non‑certified awning motors.
| Feature | UL‑Certified | Non‑Certified |
|---|---|---|
| Safety Testing | Independent lab verification | Manufacturer claim only |
| Insurance Impact | Potential premium reduction | Higher perceived risk |
| Warranty Support | Often extended coverage | Standard warranty only |
Certification Benefits
- Safety Assurance: UL testing verifies that the motor can handle overloads without fire hazards, protecting occupants and property.
- Premium Discount: Some carriers offer a modest premium reduction for UL‑listed awnings, recognizing the lower probability of electrical failures.
- Claims Confidence: Adjusters trust UL documentation, speeding up claim approval when damage occurs.
- Regulatory Alignment: UL certification helps meet NEC requirements, simplifying the permitting process in Austin.
- Resale Value: A UL‑certified system can be a selling point, indicating a well‑maintained, safe installation.
Choosing a UL‑certified motor not only safeguards your home but also eases the insurance process. In our experience, clients who upgrade to UL‑listed hardware see smoother claim handling and modest premium savings.
The Installation Photos Your Insurance Company Will Ask For After Damage
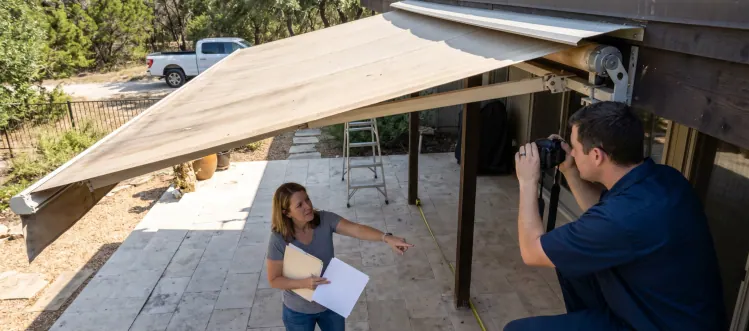
When a storm strikes, insurers request visual proof to assess the extent of awning damage. High‑resolution photos of the mounting brackets, fabric tears, and motor housing are essential for a swift claim.
Austin’s bright sunlight can create harsh shadows, so it’s best to photograph the awning during overcast conditions or use a flash to capture clear details.
Photo Checklist
- Bracket Close‑up: Show how the brackets are anchored to studs or masonry, highlighting any pull‑out damage.
- Fabric Condition: Capture tears, fading, or water stains on the fabric surface from multiple angles.
- Motor Housing: Photograph the motor housing, wiring connections, and any visible corrosion or wear.
- Overall View: Include a wide shot of the entire awning to illustrate its position and surrounding environment.
- Weather Context: If possible, include a timestamp or weather app screenshot showing wind speed at the time of damage.
Organizing these images into a single PDF and attaching them to your claim can dramatically reduce back‑and‑forth with the adjuster. In practice, homeowners who submit a complete photo set see claim decisions within days rather than weeks.
Why Professional Installation Documentation Matters More Than the Warranty Itself
A warranty promises repair or replacement, but insurers look for proof that the awning was installed correctly from the start. Professional documentation includes load calculations, anchoring methods, and compliance with local codes.
In Austin, where building codes reference the International Building Code, a detailed installation report demonstrates that the awning meets all structural requirements.
Documentation Value
- Load Calculations: Show that the awning can resist wind loads specific to your property’s exposure.
- Anchor Specification: List the type and size of fasteners used, confirming they meet pull‑out strength standards.
- Electrical Compliance: Include a diagram of the motor wiring, confirming NEC compliance and GFCI protection.
- Inspection Sign‑off: Provide the inspector’s stamp or signature, confirming final approval.
- Warranty Tie‑in: Attach the warranty booklet, linking it to the professional installation record.
When a claim is filed, the insurer’s adjuster will compare the incident to the documented installation standards. In our experience, a thorough professional report often outweighs the warranty alone, leading to faster approvals.
The Compliance Gap Between Building Permits and Insurance Requirements
A building permit ensures the awning meets local safety codes, but insurance policies have separate criteria that can be more stringent. The gap often appears in wind‑rating documentation and electrical safety proof.
Austin’s Development Services Department may approve a permit based on structural drawings, yet the insurer may still ask for motor certification and sensor calibration records.
Gap Areas
- Wind Rating Proof: Permits may note design wind load, but insurers require the manufacturer’s specific rating sheet.
- Electrical Inspection: A city inspection confirms code compliance, while insurers look for UL‑listed motor labels and GFCI circuit verification.
- Material Specs: Permits verify frame material, yet insurers may request fabric tensile strength test results.
- Sensor Settings: Building officials rarely examine wind sensor thresholds, but insurers expect documented sensor calibration.
- HOA Approvals: Some neighborhoods require HOA sign‑off, which insurers treat as an additional compliance layer.
Bridging this gap means gathering both permit paperwork and the insurer‑specific documents before a storm hits. In practice, homeowners who keep a combined folder of permits, ratings, and certifications experience smoother claim outcomes.
Securing Your Awning Investment
Understanding insurance nuances, documenting wind ratings, and keeping thorough installation records empower Austin homeowners to protect their motorized awnings from unexpected loss. The steps outlined here reduce claim denial risk and can even lower premium costs over time.
Take the next step by reviewing your current policy, gathering the necessary documents, and consulting a qualified local installer who knows Austin’s wind patterns. A proactive approach saves money and peace of mind when the next storm rolls in.
Author
Lane Frazier is a seasoned specialist in motorized shading solutions for the Austin area. With two decades of hands‑on experience installing custom awnings, he brings practical insight to every project. His deep knowledge of local building codes and insurance expectations makes his guidance especially valuable for homeowners.
Ready For a Quote?
Get your custom shade quote Today.
Free, no-pressure consultation. We measure, photograph, and send a written line-item proposal within a week. Most installs ship in 3–5 weeks.
Call the workshop
(512) 939-3446
Mon–Fri · 8a–5p CT · Austin, TX
Prefer to talk it through? Calls are answered by the same team that builds your quote — no call centers, no gatekeepers.
Custom exterior shades, motorized patio screens, awnings, and interior window treatments for Austin and Central Texas.
How To Contact Us
Austin, TX 78734
Monday - Friday 8 AM - 5 PM
navigate
Copyright © 2026 | Treaty Oak Shade Co. All Rights Reserved. | Privacy Policy